
Hot Topics Every Homeowner Should Know – summer 2026 edition!
Severe weather continues to make headlines across Illinois and much of the country. From hailstorms and damaging winds to heavy rainfall and flooding, many homeowners are discovering that not all insurance policies provide the same coverage.
As insurance professionals, we’ve noticed several topics coming up repeatedly in conversations with homeowners. Understanding these coverages before a loss occurs can help you avoid surprises and make more informed decisions about your insurance.
Here are five of the hottest home insurance topics for Summer 2026.
1. Homeowners Are Seeing Higher Deductibles for Wind & Hail Damage
Insurance companies continue to increase deductibles on homeowners’ insurance policies, especially for wind and hail claims. Understanding how your deductible works before a storm occurs can help you avoid unexpected out-of-pocket costs and make more informed insurance decisions.
Many policies now include separate wind and hail deductibles, which may be a percentage of your home’s insured value rather than a flat dollar amount. As a result, homeowners may be responsible for a much larger portion of a claim than they expect.
Before storm season, review your policy and ask your insurance agent:
- Do I have a separate wind or hail deductible?
- Is it a flat dollar amount or a percentage deductible?
- How is my roof covered if it’s damaged?
Know How Your Roof Is Covered
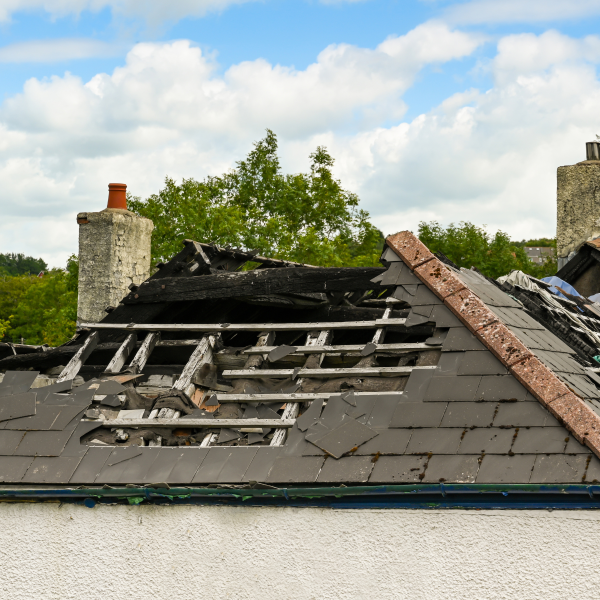
Your roof is one of the most important parts of your home—and probably what you’re thinking about after a storm blows through.
Many homeowners assume all roof claims are covered the same way, but that’s not always the case. Every policy is different, making it important to understand how your coverage works before you need it.
Understand Your Deductible
Start by reviewing your deductible.
While many homeowners have a flat dollar deductible, some policies include separate deductibles for wind or hail damage. These may be a percentage deductible rather than a fixed dollar amount. *It’s important to understand that a percentage deductible does not mean you pay a percentage of your claim. Instead, your deductible is calculated as a percentage of your home’s insured value (your dwelling coverage limit). That’s the amount you’ll pay out of pocket before your insurance coverage begins.
For example, a 2% wind and hail deductible on a home insured for $500,000 would result in a $10,000 deductible before insurance begins paying for covered damage.
Knowing your deductible ahead of time can help you plan ahead financially.
Review important policy terms, like loss settlement clauses and matching coverage.
Beyond deductibles, it’s important to understand how your policy settles roof claims.
Some policies pay replacement cost, while others may reduce the claim payment based on the age or condition of the roof. Understanding the policy’s loss settlement provisions can help you know what to expect if damage occurs.
You should also ask about matching coverage. If only one side of your home is damaged, will your insurance company pay to replace all of the siding or roofing so everything matches, or only the damaged portion? Coverage varies between insurance companies and policies.
2. Flood Insurance Is Not the Same as Sump Pump or Sewer Backup Coverage
This is one of the most common misconceptions in homeowners insurance.
Many homeowners believe that water damage is automatically covered. In reality, the source of the water often determines whether coverage applies.
Sump Pump Failure and Sewer Backup
Damage caused by a sump pump failure or sewer backup is not automatically included on most homeowners insurance policies. However, this coverage is often available as an endorsement for an additional premium.
If your basement contains finished living space, electronics, furniture, or other valuable belongings, this is an important coverage to discuss with your insurance agent.
Flood Insurance
Flood insurance is typically a separate insurance policy.
Damage caused by rising water entering your home from outside—such as overflowing rivers, heavy rainfall, or flash flooding—is generally not covered under a standard homeowners insurance policy.
Even homes located outside of designated flood zones can experience flooding. Depending on your property’s location and risk, flood insurance may be worth considering.
Understanding the difference between flood insurance and sump pump or sewer backup coverage can help ensure you’re protected against the types of water losses most likely to affect your home.
3. Don’t Overlook Ordinance or Law Coverage
Many homeowners have never heard of Ordinance or Law coverage until after a major claim.
If your home suffers significant damage, local building codes may require portions of your home to be rebuilt or upgraded to meet current construction standards—even if those features weren’t required when your home was originally built.
Examples may include:
- Updated electrical systems
- New plumbing requirements
- Energy-efficient insulation
- Roof or structural code upgrades
- Accessibility or safety improvements
These additional rebuilding costs can add up quickly, especially for older homes.
Ordinance or Law coverage can help pay for the increased costs associated with complying with current building codes after a covered loss. If you own an older home, this is an especially important coverage to review with your insurance professional.
4. If You Live in a Condo or HOA, Understand Your Association’s Insurance
Many condo owners and homeowners association (HOA) members assume the association’s insurance protects them from every loss. In reality, the association’s policy and your personal insurance policy work together—and understanding where one ends and the other begins is essential.
Review Your Association’s Financial Health
A well-managed association should maintain adequate reserve funds for future repairs and unexpected expenses.
If reserves are low or the association is underfunded, homeowners could face special assessments following major losses or building repairs.
Understand the Association’s Insurance
Ask questions about the association’s master insurance policy, including:
- Does the policy have a large wind or hail deductible?
- Is the deductible a flat dollar amount or a percentage?
- Is there a separate deductible for each building?
- Could homeowners be responsible for a portion of the deductible after a claim?
These details can have a significant financial impact after a major storm.
Know Your Responsibilities
Your association’s insurance policy does not eliminate the need for your own insurance.
Condo owners should understand what the association insures, what their personal condo policy covers, and whether they need additional protection for improvements, personal property, loss assessments, or liability.
Knowing your rights and responsibilities before a loss occurs can help prevent unexpected expenses and coverage gaps.
5. Create a Home Inventory Before You Need It.
After a fire, tornado, theft, or other major loss, one of the hardest parts of filing a claim is remembering everything you owned.
A home inventory can make the claims process faster and more accurate by helping document your personal belongings before a loss occurs.
Creating an inventory doesn’t have to be complicated. Start by walking through your home with your smartphone and taking photos or videos of each room. Open closets, cabinets, and drawers, and capture valuable items such as electronics, appliances, furniture, jewelry, and collectibles. If possible, save receipts, appraisals, or serial numbers for higher-value items.
Store your inventory somewhere safe, such as cloud storage or another location outside your home, so it’s available if you ever need it.
Keeping your home inventory up to date—especially after major purchases or renovations—can make recovering from a loss much less stressful.
The Bottom Line
Insurance policies are not all the same, and some of the most important coverages are often the ones homeowners don’t think about until after a claim.
Whether you’re reviewing your roof coverage, understanding water damage protection, evaluating Ordinance or Law coverage, or learning how your homeowners association’s insurance works, taking the time to review your policy today can make a significant difference tomorrow.
At Railside Citrus Insurance Agency, we believe insurance is more than simply purchasing a policy—it’s understanding how your coverage works when you need it most. If you’d like to review your homeowners insurance or compare your current coverage with other options, our team is happy to help.